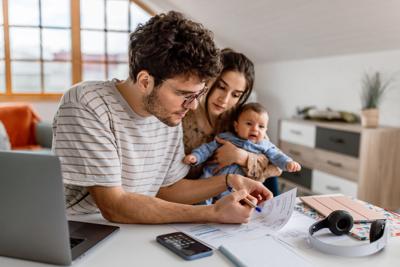

Young parents taking care for cute little baby while doing financial planning at home
A single-income household with children is probably more common than many people realize and more workable than the typical financial-advice column suggests. About one in four households with children in the U.S. has only one wage earner, and many of those households are running healthy budgets, building savings, and making long-term progress despite the income structure. The math is different from a dual-income household, but it isn't impossible — it's a different optimization problem with its own playbook. This is what that playbook actually could look like.
Start With the Real Cost Comparison
The first useful exercise for a single-income household is understanding what the second income would have cost. The headline pay is rarely the actual contribution to the household.
People are also reading…
For a typical second earner at $50,000 gross: - Federal and state taxes: ~$8,000–$12,000 - Social Security and Medicare: ~$3,825 - Childcare for one child (if working full-time): $12,000–$25,000 - Commuting, work wardrobe, lunches out: ~$3,000–$5,000 - Higher convenience spending (takeout, services, time-savers): ~$2,000–$4,000
The $50,000 second income often nets out at $5,000–$20,000 of actual added household resources. For some households, that's still worth it. For many, the gap between gross income and net contribution makes single-income parenting more economically rational than the headline numbers suggest.
This isn't to argue against second incomes — it's to argue for honest math when comparing the two structures.
The Three Budget Categories That Matter Most
Single-income households may tend to thrive when they hold three budget categories tighter than dual-income households often do:
1. Housing cost share. The standard "30% of gross income on housing" rule sometimes could push single-income households into homes they can't sustain. A working benchmark is 25% of gross or less for single-income households, which leaves more margin for the categories below.
2. Transportation cost share. Two cars at financed prices may be a heavy lift on one income. Many single-income households run more efficiently with one car, or with one financed car and one fully owned older vehicle. The savings on insurance, maintenance, and payments often run $5,000–$10,000 per year.
3. Recurring subscriptions. Easy to ignore individually, painful in aggregate. Streaming services, meal kits, software subscriptions, gym memberships, kids' activity subscriptions. A quarterly audit of recurring charges typically surfaces $50–$200 per month of cancellations that don't reduce quality of life.
The Income-Smoothing Tools That Help
Single-income households face more income concentration risk than dual-income households — if one earner has a setback, there's no second income to absorb it. Two practical tools reduce that risk:
Disability insurance. Often overlooked. Short-term and long-term disability coverage replaces a percentage of income if the earner can't work due to injury or illness. Many employers offer it as a low-cost benefit; supplemental coverage is available individually for $20–$80 per month for most households. The protection it offers — typically 60% income replacement — is the single most useful insurance product for a single-income family beyond life insurance.
A larger emergency fund. Where a dual-income household might aim for three months of expenses, a single-income household benefits from six months. The buffer absorbs job-loss risk that the second income would otherwise absorb.
How Tax Planning Shifts on One Income
A single-income household has tax tools that dual-income households often can't use as effectively:
Married filing jointly with one earner. A non-earning spouse's portion of the standard deduction and tax bracket capacity reduces the earner's effective tax rate. The household keeps more of each dollar than two earners splitting the same total gross.
Spousal IRA contributions. The non-earning spouse can contribute to an IRA based on the working spouse's income, doubling the household's tax-advantaged retirement savings space.
No "marriage penalty" at higher incomes. Two-earner couples at higher combined incomes sometimes pay more in taxes than they would as single filers; single-income married households don't face this issue.
A quick conversation with a tax professional in the first year of single-income status often surfaces $1,000–$3,000 in annual tax efficiency the household wasn't capturing.
The Long-Term Plan Most Single-Income Families Should Have
Single-income households may benefit enormously from structured long-term planning. Three pieces tend to matter most:
A retirement plan that doesn't depend on a second income kicking in later. If the working spouse contributes 10%–15% of gross to retirement consistently — through a 401(k), IRA, or Roth IRA — most single-income households have potential to build the same long-term wealth as dual-income households contributing 5%–7% each. Consistency on one income often beats inconsistency on two.
A housing plan with built-in flexibility. Buying a home with a mortgage payment well below maximum affordability creates breathing room for life changes — a second child, a career shift, a stretch year. First-time buyer programs, down payment assistance, and conservative loan terms all help. A home purchased with breathing room serves a single-income household better than one purchased at the affordability ceiling.
An education savings plan that's modest but consistent. A 529 plan with $100–$200 per month, contributed across 18 years, compounds into meaningful college savings without straining current cash flow.
How the Survey Data Fits In
Rocket Mortgage findings from a national parents study show — based on a survey of 1,007 parents and caregivers — that family financial decisions are increasingly shaped by careful planning around current and future household income structure. For single-income households, that careful planning isn't optional; it's the lever that turns a tight income structure into a working one.
The Bottom Line
Single-income parenting works when the household runs lean on the three big cost categories, builds protection through disability insurance and a larger emergency fund, captures the tax efficiencies the structure offers, and stays consistent on long-term contributions. These aren't dramatic moves. They're small, durable habits that compound over years and produce the same long-term outcomes as a higher-income, higher-cost two-earner household — sometimes better, because the lifestyle that produced them tends to stick.